No Roof Beats Texas Hail. Here's What Actually Helps.
There is no roofing material that fully stands up to Texas hail. Not one. What does exist is a real difference between a shingle that fractures on the first storm and one that doesn't.
Call (945) 231-3781 for a Free QuoteIf you just moved to Texas, you probably look around every spring, then every summer, then every fall, and then yes, every winter, and wonder what in the world is going on with the weather.
Everybody here feels the same way. It's part of why there are so many roofers in DFW. At least it's not foundations, though around here the ground moves too, which is a different article.
Here's something most roofers won't put on their website: there is no roofing material that fully stands up to Texas hail. Not one. Anybody telling you otherwise is selling something.
What does exist is a meaningful difference between a shingle that fractures on the first real storm and one that doesn't. That difference is worth understanding, because it affects your roof, your premium, and how your next claim goes.
What the job actually looks like
Some context on why roofing quality varies so much here.
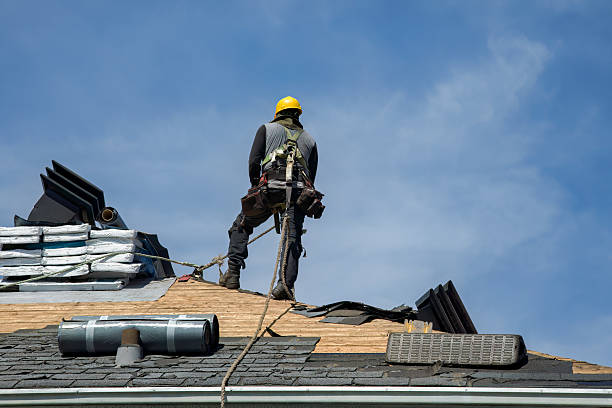
You're standing on the side of a mountain all day for your living, baking in the Texas sun. It's one of the more dangerous trades there is, and it's hard on the body and the mind in a way that's difficult to explain to anyone who hasn't done it.
On top of that, roofing in North Texas is a race. A crew has to get in, do the work correctly, and be finished before the weather turns, before the wind picks up, or before dark on the final day. A roof left open overnight when a storm rolls through is a much bigger problem than the one you called about.
That's why crew experience matters more than shingle brand. The same material installed by two different crews gives you two different roofs.
How shingles actually get rated
The standard is UL 2218. It's simple: a steel ball gets dropped onto a shingle sample from a set height, twice in the same spot. The shingle passes if the mat doesn't crack, tear, or fracture.
Bigger ball, higher class.
| Class | Steel ball | Drop height |
|---|---|---|
| Class 1 | 1.25 inch | 12 feet |
| Class 2 | 1.5 inch | 15 feet |
| Class 3 | 1.75 inch | 17 feet |
| Class 4 | 2 inch | 20 feet |
Standard architectural shingles don't pass Class 4. That's the whole distinction.
Two things worth being clear about.
Class 4 is not hail-proof. It's rated to survive a 2-inch impact. North Texas produces hail bigger than that, and when it does, Class 4 roofs get damaged too. The rating buys you a much better chance in the storms that actually happen most often, which is genuinely valuable. It does not buy you immunity.
The rating is about the mat, not the surface. A Class 4 shingle can still lose granules and look beaten up. What it resists is the fracture underneath, which is the failure that actually lets water in.
The insurance side, which is where it gets interesting
Texas requires homeowners carriers to offer a discount for impact-resistant roofing. This isn't a promotion a contractor invented, it's in the Insurance Code.
In practice, most North Texas carriers discount somewhere between 15% and 35% on the wind and hail portion of the premium for Class 4, and less for Class 3. The exact number depends entirely on your carrier and your policy, so the only reliable way to know yours is to ask your agent before you commit to anything.
The process:
- Your contractor gives you the manufacturer's UL 2218 certification for the specific product installed
- TDI Form PC068, the Impact-Resistant Roofing Installation Form, gets completed
- You submit both to your carrier
- The credit shows up at renewal, not immediately
If a contractor can't produce the manufacturer certification for the exact product they installed, that's a problem. Without it there's no discount.
The catch nobody mentions
Here's the part that doesn't make it into most Class 4 sales pitches.
So you can end up trading a real premium discount for reduced coverage on exactly the peril you were protecting against. Sometimes that trade makes sense. Sometimes it very much doesn't. It depends on your deductible, how long you plan to own the house, and how the endorsement is written.
Read it before you sign it, and ask your agent directly if the discount is conditioned on an exclusion. That question is the whole ballgame and most homeowners never think to ask it.
Second thing worth knowing: carriers replace like kind and quality. If you had Class 3, an approved claim gets you Class 3. Upgrading to Class 4 during a claim usually means covering the material difference yourself. That's a decision worth making deliberately rather than discovering at the end.
Where we land on it
We're not going to tell you Class 4 makes your roof bulletproof, because it doesn't, and you'd find that out in the next big storm.
What we'll tell you is that in a hail corridor like Collin County, the higher rating is usually worth considering, the insurance discount is real, and the exclusion question needs answering before you decide.
And when you call us, we try to fix it before we try to sell you a replacement. If a repair holds, we'll quote the repair. That's covered in more detail in roof repair or replacement, and what a real inspection involves is in what a hail damage roof inspection actually involves.
About us
Family-owned, working DFW since 1997. Texas contractor license #1223708, HAAG certified inspector #991904014, RCAT certified. 4.8 stars across 145 Google reviews. Lifetime transferable workmanship warranty on everything we install.
Call (945) 231-3781 or email info@autographconstruction.com.
Questions? Call (945) 231-3781
← Back to blog